What is Cannabis Insurance?
What is Cannabis Insurance?
When we get asked what Cannabis Insurance is, you would be surprised how many think of a policy that covers you if you lose your pot (I mean, hey, it’s valuable!). Cannabis insurance is actually designed with the commercial business in mind, to cover a lot of the vulnerabilities any business may need to protect (by law or for financial reasons).
In California, there are different types of cannabis business licenses that are permitted. They are:
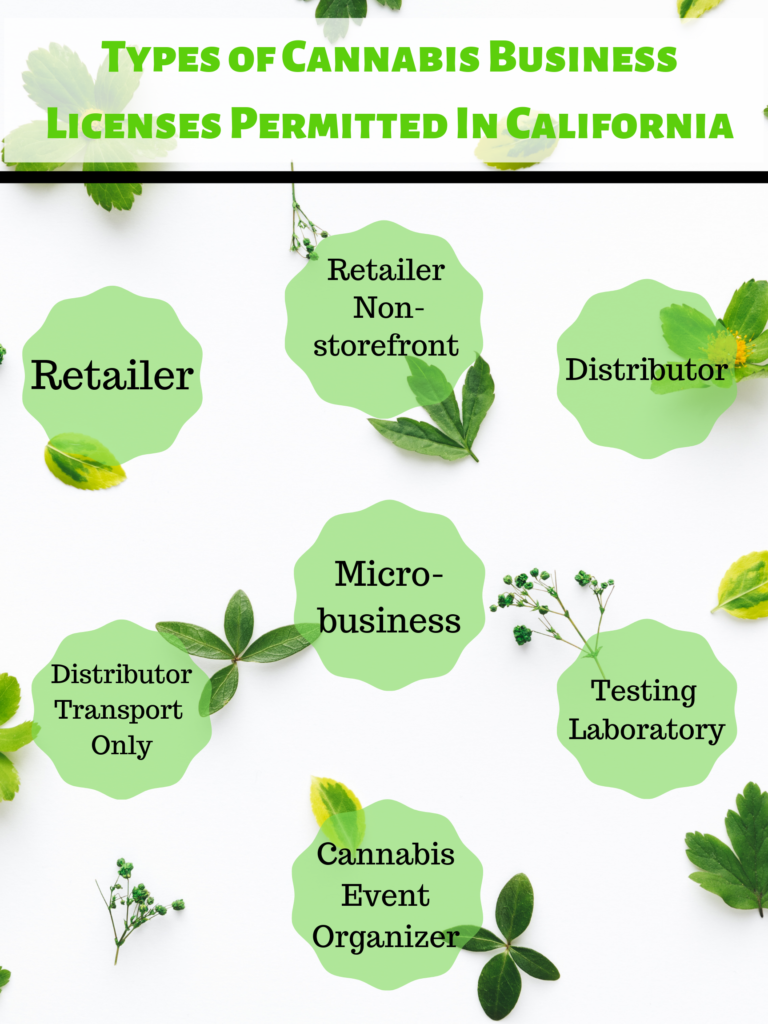
Retailer License
Cannabis businesses who have a storefront with retail sales and walk-in customers or delivery.
Retailer Nonstorefront License
These cannabis retailers must have licensed premises but no public access.
Distributor License
This includes Cannabis product transportation, the arrangement of testing products, ensuring compliance with requirements of packaging and labeling regulations.
Distributor – Transport Only License
Transporting of cannabis between licensed cultivators, manufacturers, distributors.
Microbusiness License
This is for license holders with cannabis cultivation operations up to 10,000 square feet. This also allows a licensee to act as a distributor, a Level 1 manufacturer (Type 6), and retailer (specified in the application). A licensee must engage in at least three of the four commercial cannabis activities listed.
Testing Laboratory License
For Laboratory testing of cannabis products.
Cannabis Event Organizer
Only licensed to hold cannabis events unless a separate license has been granted.
Additionally, there are designations for Adult-Use and Medicinal License.
Part of the application process for local and state licensing is to obtain a surety bond. In California, Section 15002 of the cannabis regulations requires an annual license application to include a surety bond of at least $5,000 payable to the State for each licensed premises (source: DCC Form 8113). Other states set their own bond rules; see Cannabis Surety Bonds for current requirements and sources. What you pay for a bond depends mainly on the bond amount required, your credit and financials, and your license type, so the quickest way to know your cost is to request a bond quote or call (916) 967-7715. If you’re not sure whether your state requires a cannabis surety bond, contact us and we’ll let you know.
Once the applicant is granted a state-issued license to operate a cannabis-related business and your license is being processed, it’s a good time to secure additional cannabis insurance for the business. There are of course factors to consider when you begin looking for commercial cannabis insurance. Some of the factors to consider are license type, whether there will be employees, business operations, just to mention a few. Every situation is different, but at the least, you’ll want to get a General Liability insurance policy.
What is good coverage, and Why?
Commercial cannabis insurance for cannabis businesses isn’t much different than other types of commercial insurance. Your general liability limits are often set by your landlord, local ordinances or contracts, so confirm those requirements before you choose limits. If you own the property where your business is located, you will also need good property coverage. Even if you are renting, some landlords require you to carry this coverage. If you’re selling your own cannabis products, product liability is a must have. Additionally, if you’re planning on hiring employees, most states require businesses with employees to carry Workers Compensation insurance, and some states also count “volunteers” who work for trade, so confirm the rules where you operate.
Commercial cannabis insurance is an important expenditure that you should never go without. Assess your investment, look at your situation, consider your business operations carefully and figure out what commercial cannabis insurance coverage you will need. It’s always better to be safe than sorry and if you must pay a little now, it could protect you from having to pay a lot more later. It’s worth it.