What is Cannabis Insurance?
What is Cannabis Insurance?
When we get asked what Cannabis Insurance is, you would be surprised how many think of a policy that covers you if you lose your pot (I mean, hey, it’s valuable!). Cannabis insurance is actually designed with the commercial business in mind, to cover a lot of the vulnerabilities any business may need to protect (by law or for financial reasons).
Insuring a cannabis business? Request a quote or call (916) 967-7715. Writing cannabis insurance since 2009, licensed in all 50 states.
In California, there are different types of cannabis business licenses that are permitted. They are:
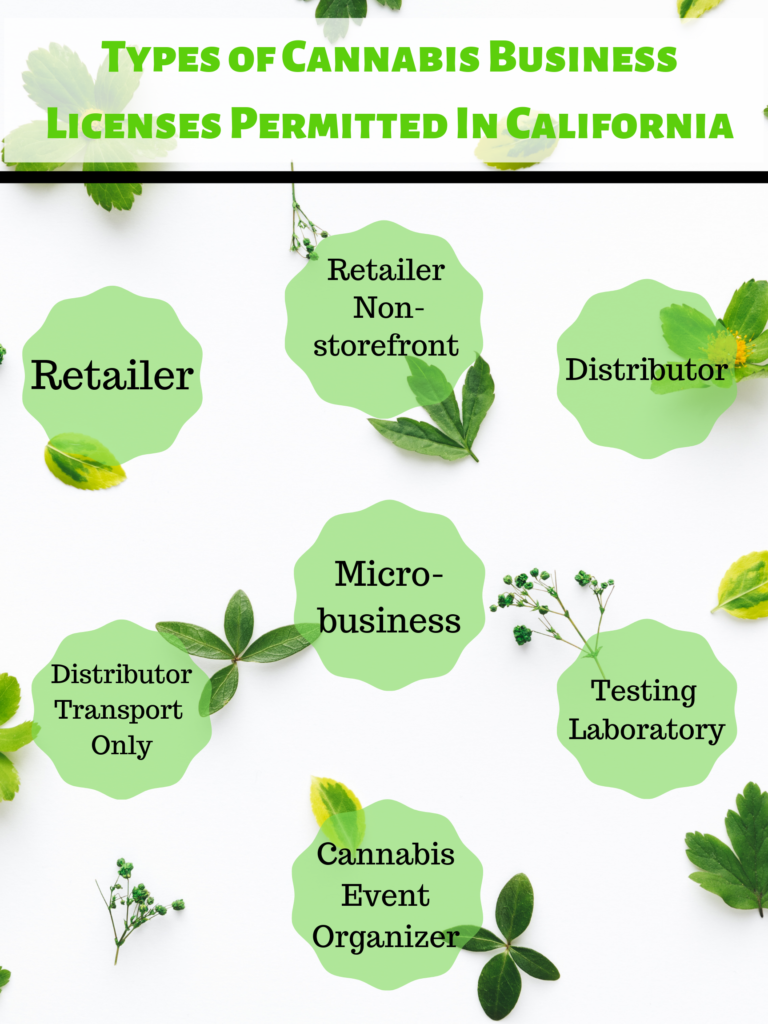
Retailer License
Cannabis businesses who have a storefront with retail sales and walk-in customers or delivery.
Retailer Nonstorefront License
These cannabis retailers must have licensed premises but no public access.
Distributor License
This includes Cannabis product transportation, the arrangement of testing products, ensuring compliance with requirements of packaging and labeling regulations.
Distributor – Transport Only License
Transporting of cannabis between licensed cultivators, manufacturers, distributors.
Microbusiness License
This is for license holders with cannabis cultivation operations up to 10,000 square feet. This also allows a licensee to act as a distributor, a Level 1 manufacturer (Type 6), and retailer (specified in the application). A licensee must engage in at least three of the four commercial cannabis activities listed.
Testing Laboratory License
For Laboratory testing of cannabis products.
Cannabis Event Organizer
Only licensed to hold cannabis events unless a separate license has been granted.
Additionally, there are designations for Adult-Use and Medicinal License.
Part of the application process for local and state licensing is to obtain a surety bond. In California, Section 15002 of the cannabis regulations requires an annual license application to include a surety bond of at least $5,000 payable to the State for each licensed premises (source: DCC Form 8113). Other states set their own bond rules; see Cannabis Surety Bonds for current requirements and sources. What you pay for a bond depends mainly on the bond amount required, your credit and financials, and your license type, so the quickest way to know your cost is to request a bond quote or call (916) 967-7715. If you’re not sure whether your state requires a cannabis surety bond, contact us and we’ll let you know.
Once the applicant is granted a state-issued license to operate a cannabis-related business and your license is being processed, it’s a good time to secure additional cannabis insurance for the business. There are of course factors to consider when you begin looking for commercial cannabis insurance. Some of the factors to consider are license type, whether there will be employees, business operations, just to mention a few. Every situation is different, but at the least, you’ll want to get a General Liability insurance policy.
What is good coverage, and Why?
Commercial cannabis insurance for cannabis businesses isn’t much different than other types of commercial insurance. Your general liability limits are often set by your landlord, local ordinances or contracts, so confirm those requirements before you choose limits. If you own the property where your business is located, you will also need good property coverage. Even if you are renting, some landlords require you to carry this coverage. If you’re selling your own cannabis products, product liability is a must have. Additionally, if you’re planning on hiring employees, most states require businesses with employees to carry Workers Compensation insurance, and some states also count “volunteers” who work for trade, so confirm the rules where you operate.
Commercial cannabis insurance is an important expenditure that you should never go without. Assess your investment, look at your situation, consider your business operations carefully and figure out what commercial cannabis insurance coverage you will need. It’s always better to be safe than sorry: the right coverage now can protect you from a much larger loss later.
What affects your cannabis insurance quote
We do not publish prices, because every quote depends on underwriting. These are the details insurers typically look at. Having them ready makes your quote faster.
- License type and operations: cultivation, manufacturing, distribution, retail, delivery or testing
- Products you make or sell, such as flower, edibles, vapes or concentrates
- The states and locations you operate in
- Buildings, equipment, crop and inventory you need to insure
- Revenue, payroll and number of employees
- Vehicles, drivers and product in transit if you deliver or distribute
- Security, alarm, camera and cash-handling controls
- Past claims and losses
- Limits, deductibles and certificate wording required by your state, landlord, lender or contracts
Need a bond for your license too? See cannabis surety bond requirements by state.
Request a Quote or call (916) 967-7715. Writing cannabis insurance since 2009, licensed in all 50 states.
Cannabis insurance FAQ
What insurance does a cannabis business need?
Most cannabis businesses start with general liability, product liability if they make or sell products, property coverage for the building, equipment and inventory, and workers' compensation once they have employees. Depending on the license, add crop coverage, cargo and commercial auto, a surety bond and coverage required by your lease.
Is cannabis insurance required by law?
Some of it is. Requirements come from state cannabis regulators, local permits, landlords and contracts, and they differ by license type. California, for example, requires a surety bond for each licensed premises and sets a liability insurance minimum for distributors. Confirm the rules for your state and license.
Do you insure cannabis businesses outside California?
Yes. The Cannabis Coverage Company has written cannabis insurance since 2009 and is licensed in all 50 states, so we work with licensed cannabis businesses in states with a legal market.
What affects the cost of cannabis insurance?
We don't publish prices because every quote depends on underwriting. The main factors are your license type and operations, revenue, inventory and property values, security, the states you operate in, claims history and the limits you choose. Request a quote or call (916) 967-7715.
State rules: See cannabis insurance requirements by state, with a link to the regulation or statute behind each summary.
Request a cannabis insurance quote
Tell us your license type, operations, locations and the coverage or certificates you need. The Cannabis Coverage Company has written cannabis insurance since 2009 and is licensed in all 50 states (CA Lic. #0G22084).